Management and professional risk is the suite of cover that protects the business when something doesn’t go to plan, a dispute, a regulatory matter, a breach or an allegation against a director or officer. We structure that cover deliberately, around the specific exposures of each business we work with, not off a standard template.
Our Services
Professional Indemnity
Directors & Officers and Management Liability
Cyber & Technology Liability
Public Liability
Medical Indemnity Insurance
Indemnity cover for health professionals and health businesses, including telehealth providers and pharmacists, against claims arising from the care, advice, or services they provide. A specialised form of professional indemnity, structured around the particular risks and regulatory environment of the health sector.
How we work with you
Every engagement is different, but the shape of the work is consistent. Here’s what to expect from first contact to policies in place.
01
Introduction
A first conversation to understand your business, your current cover and what’s brought you to us. We use it to decide if we’re the right broker for your situation and we’ll tell you honestly if we’re not.
02
Needs analysis and capability validation
We work through your specific exposures in detail, your contracts, your client base, your regulatory environment. This usually means meeting you on site or wherever the business runs, because the right cover comes from seeing how things work.
03
Data capture and expectations
We collect the information needed to go to market, set clear expectations on next steps and confirm a timeline, typically two to three weeks to indicative terms.
04
Summary report
We issue a written summary of what we’ve found, where the gaps and opportunities sit and what we recommend taking to market.
05
Discussion and
decisions
We walk through the report with you. You decide the direction, we document the brief and we agree the approach before going to market.
06
Placement and negotiation
We complete the terms with underwriters, negotiating wording, limits, deductibles and structure directly with the people making the underwriting decisions.
07
Documentation and policies
We issue documentation, invoices and policies. You have everything you need in writing, with clear records of what’s been placed and on what terms.
08
Ongoing claims and review
We stay across your business between renewals, handling claims, managing mid-term changes and keeping you informed on market shifts that affect your cover.
Renewals are where most brokers stop thinking, we don’t
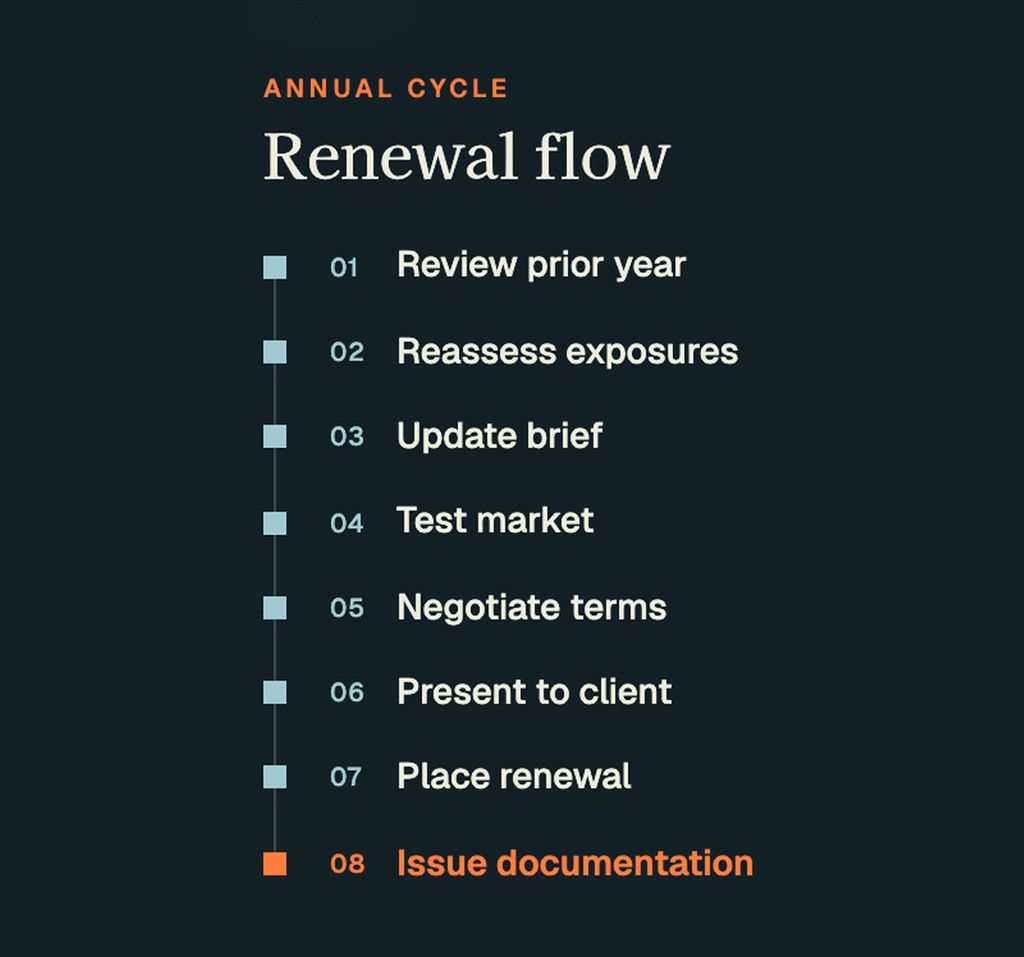
A renewal is the moment to look at the cover seriously, not to roll it over. Our renewal process starts well before the policy is due, we review the year’s claims activity, reassess the business’s exposures, pressure-test the wording against any changes in your operations and rebuild the brief if needed. Only then do we go back to market and only with underwriters who write this class of business properly.
Already in the middle of a claim, or worried one’s coming?
Placing the right cover is the start of the work, not the end. If a claim has been notified or you’re worried about something brewing, our claims support team is built around guiding clients through the process, including clients we haven’t placed cover for.
What our clients say
Lorem ipsum dolor sit amet consectetur. Risus ornare facilisi volutpat et netus facilisi amet nunc diam. Risus blandit eu nunc sem blandit pretium. Sodales sed fermentum aliquam consequat cum tincidunt id scelerisque interdum. Scelerisque mauris cursus quam convallis nisl vitae.
Lorem ipsum dolor sit amet consectetur. Risus ornare facilisi volutpat et netus facilisi amet nunc diam. Risus blandit eu nunc sem blandit pretium. Sodales sed fermentum aliquam consequat cum tincidunt id scelerisque interdum. Scelerisque mauris cursus quam convallis nisl vitae.
Lorem ipsum dolor sit amet consectetur. Risus ornare facilisi volutpat et netus facilisi amet nunc diam. Risus blandit eu nunc sem blandit pretium. Sodales sed fermentum aliquam consequat cum tincidunt id scelerisque interdum. Scelerisque mauris cursus quam convallis nisl vitae.
Lorem ipsum dolor sit amet consectetur. Risus ornare facilisi volutpat et netus facilisi amet nunc diam. Risus blandit eu nunc sem blandit pretium. Sodales sed fermentum aliquam consequat cum tincidunt id scelerisque interdum. Scelerisque mauris cursus quam convallis nisl vitae.
Talk to a specialist team
When you contact Indemnity PRO, you speak to a senior insurance specialist, not a call centre or quote bot. We’ll take the time to understand your situation and tell you within one conversation whether we’re the right broker for it.